

Zip
by Zip, Co.
4.7
- Safety
- 100% Safe
- Category
- Shopping
- Ratings
- 4.7
- Price
- Free
- Download
- 5.00M
This app is secure, reliable, free to install, and offers fast downloads without any risks or malware.
Screenshots
 Analysis by Getfullapps
I tried Zip as a shopping companion rather than treating it like a simple coupon app, and that distinction matters. It is a free shopping app from Zip, Co. that lets you arrange flexible payments for purchases at participating checkout points, including places where Visa is accepted. The idea is straightforward: instead of paying the entire amount immediately, you use Zip’s payment option and manage the purchase through the app.
That can be useful when a necessary purchase arrives at an awkward time, but it is not automatically a money-saving tool. In my experience, the real value comes from planning and repayment discipline, not from the word “free” on the download button. The app costs nothing to install, yet using a flexible payment service still requires careful attention to the terms shown for each transaction.
Zip sits in the shopping category, and its broad appeal is reflected in a 4.7 average from around 106 thousand ratings. It has passed 5 million installs, which makes it a familiar option rather than a niche experiment. I found it most interesting as a payment layer that follows me beyond one retailer’s own checkout, although that wider reach also makes personal budgeting more important.
How Zip fits into everyday shopping
The basic experience begins with installing the app, creating or accessing a Zip account, and using the service when shopping. The exact path can depend on the retailer and checkout context, so I would not treat every purchase as identical. The useful mental model is that Zip helps split the cost of an eligible purchase into a flexible payment arrangement instead of making the app a conventional store with its own product catalog.
That makes it different from a standard shopping app. A retailer’s app may be better for browsing products, tracking store-specific promotions, or collecting loyalty rewards. A bank card gives you a familiar one-step payment and leaves the purchase in your normal account history. Zip adds another layer: the purchase is connected to a separate repayment schedule that needs monitoring.
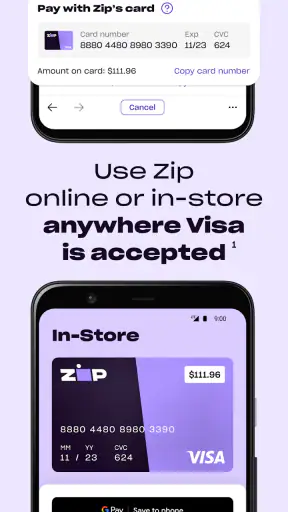
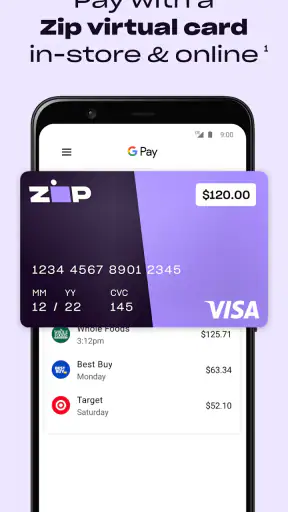
The “pay anywhere” positioning is appealing because I do not have to limit the idea to one particular shop. The service is intended for use at places that accept Visa, although that should not be read as a guarantee that every transaction will work exactly the same way. Checkout support, merchant rules, and account eligibility can affect the experience. I would always check the payment screen before assuming a planned purchase can use Zip.
One practical scenario is replacing a broken household item shortly before payday. With a normal debit-card purchase, the full amount leaves the account immediately. With Zip, I can look at the available payment arrangement, confirm what is due now, and decide whether the remaining installments fit my upcoming budget. That can reduce immediate pressure, but it does not reduce the total responsibility. The purchase still has to be paid for.
Articles to Explore Next

Uber Eats Makes Dinner Easier to Manage, but the Fees Add Up

Google Photos Turns a Camera Roll Into a Library You Can Find Your Way Through

Canva on Mobile: Adopt It for Quick Visuals, Test It for Demanding Work

Google Drive Keeps Work Moving Until It Doesn’t

Switching to Weather - By Xiaomi Means Relearning Your Forecast Routine

Ludo King and the Social Life of a Lucky Six
What the free download actually means
Zip is listed as free, so there is no purchase price for downloading the app itself. That is useful for trying the interface and seeing whether the service suits my shopping habits without paying an upfront app fee. However, free access should not be confused with free financing. The cost of any transaction depends on the terms presented at the time, and those terms deserve the same attention I would give to a credit-card purchase or another payment plan.
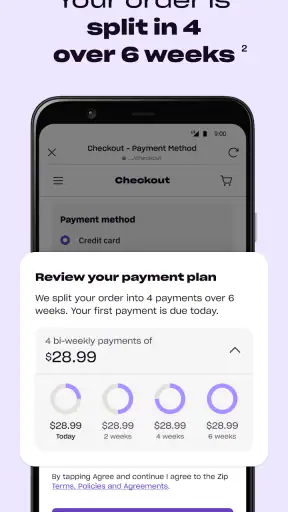
I would approach the first transaction as a test of clarity. Before confirming, I would check the amount due immediately, the later payment dates, the total repayment amount, and any applicable charges shown in the checkout flow. If those details are not comfortable to review, Zip is probably not the right tool for that purchase. A payment app should make the schedule understandable enough that I can remember it without guessing.
This is also why I would not compare Zip with a free shopping browser on a simple download-price basis. A browser helps me find products; Zip changes how I pay for them. The app can be free to install while the payment arrangement carries obligations. That distinction is the most important value question here.
Where the app delivers practical value
The strongest benefit is flexibility at the moment of purchase. If I have a predictable income but need to spread a larger expense across several pay periods, a structured schedule can be easier to manage than putting everything on a general-purpose credit card and calculating the consequences later. Zip presents the payment plan around the purchase, which can make the commitment more visible.
That visibility can help with a specific workflow: I can decide on a maximum amount before browsing, use Zip only if the displayed schedule stays within that limit, and then record the future payments in my personal budget. The important step is setting the limit before seeing the product, not after getting attached to it. Otherwise, flexible payments can make an item feel cheaper than it really is.
Another useful point is reach. Because Zip is designed to work wherever Visa is accepted, it may be more convenient than a retailer-specific installment option when I shop across different stores. I do not need to learn a completely different payment system for every merchant. Still, I would treat Visa acceptance as a starting condition rather than a promise that every checkout will be approved.
The app can also be helpful for people who want a separate place to review their Zip commitments instead of relying only on memory. That separation is a strength when it encourages checking upcoming payments. It becomes a weakness if it causes me to forget that those obligations exist outside my main banking app. I would keep Zip’s schedule visible alongside my regular budget rather than assuming the app alone will prevent overspending.
Small habits that make the service safer to use
My first tip is to calculate the purchase in two ways: the full amount and the amount that will leave the account immediately. The first tells me whether I can truly afford the item; the second tells me whether today’s cash flow can handle the transaction. Looking only at the initial payment is the easiest way to make a nonessential purchase seem manageable.
My second tip is to avoid stacking several “small” Zip purchases. Each individual schedule may look harmless, but the combined future payments can become difficult to see. I would write down every active commitment, group them by payment date, and pause before opening another one. This is especially important when shopping for clothing, electronics, or seasonal items that are easy to buy impulsively.
A third useful habit is to use Zip for a planned need rather than as a reason to increase the basket. I would decide on the product and a maximum total first, then use the app only if the arrangement is clear. If the flexible option encourages me to choose a more expensive version, the convenience has stopped delivering value.
Finally, I would keep enough money available for the scheduled payments even if the item is returned, delayed, or no longer feels worthwhile. A return may involve a separate process with the retailer, while the payment schedule remains something I need to understand and monitor. I would not assume that sending an item back instantly resolves every payment detail.
The tradeoffs I noticed
The main friction is psychological rather than technical: dividing a purchase into installments can make the total feel less immediate. That is convenient when the expense is necessary and planned, but risky when the purchase is discretionary. Zip does not replace the need for a budget, and it should not be used to make an unaffordable item appear affordable.
There is also a comparison problem. A traditional credit card may offer a familiar statement, existing spending controls, and a single place to review transactions. A retailer’s own payment plan may be smoother at that retailer. Zip’s advantage is broader shopping flexibility, but that advantage is less important if I mostly buy from one store or already have a payment method whose terms I understand well.
Approval and checkout can also be less predictable than paying directly with a card. The app’s broad acceptance message does not eliminate the possibility of merchant-specific conditions or a transaction that does not proceed as expected. For a time-sensitive purchase, I would keep a conventional payment method available rather than relying on Zip as the only option.
Another tradeoff is account management. Adding a separate payment service means another app, another place to check, and another schedule to remember. For an organized user, that can be manageable. For someone who already misses card due dates or has several subscriptions scattered across accounts, an additional repayment stream may create more stress than convenience.
I also would not use Zip as an emergency fund substitute. If an expense is genuinely urgent and I have no realistic way to cover the later payments, spreading it out only postpones the problem. In that situation, a direct conversation with the provider, a carefully planned purchase, or waiting for a lower-cost alternative may be wiser.
Who is most likely to benefit
Zip is a reasonable fit for shoppers who have steady income, understand their monthly cash flow, and want flexibility across more than one retailer. It can be especially practical for a planned household replacement, a necessary purchase that falls between paydays, or a larger order where the displayed schedule is easy to fit into an existing budget.
I can also see value for someone who prefers separating a planned purchase from everyday debit spending. The app gives that person a deliberate checkpoint: review the arrangement, confirm the amount, and decide whether to proceed. Used that way, Zip supports a budgeting decision rather than replacing one.
It is less suitable for anyone who tends to shop impulsively, has irregular income with little reserve, or already struggles to track recurring obligations. I would also skip it for low-cost items that I can comfortably pay for today. Adding a payment schedule to a purchase that does not need one creates administrative work without a meaningful benefit.
People who want rewards, price comparison, or product discovery should look elsewhere or use a separate shopping tool alongside it. Zip’s central purpose is payment flexibility, not being a complete marketplace. Likewise, someone who wants a single consolidated statement may prefer using an existing card or bank payment method.
Device support and current app details
The app supports devices running iOS or Android software from version 8.1 onward, so its stated minimum is not limited to recent phones. I would still keep the app updated because payment applications handle time-sensitive account information, and older operating systems can offer a less comfortable experience even when they meet the minimum requirement.
The current version is 1.250.4. Zip, Co. is the developer, and the app has an Everyone content rating, which fits a shopping and payment utility intended for a broad audience. The rating does not mean every financial decision is suitable for every person, though. Younger users and anyone sharing household finances should understand who is responsible for the repayment arrangement before using it.
Zip was released on May 24, 2019, so it is not a brand-new entry in mobile shopping. Its established presence and large install base make it easier to regard as a mainstream option, but popularity should not replace reading the terms for an individual purchase. Payment products can still vary in usefulness depending on personal circumstances.
My buy-or-skip verdict
I would recommend trying Zip to a careful shopper who wants a free-to-download way to explore flexible payments across different merchants. The value is not that the app makes shopping cheaper; the value is that it can make the timing of a planned payment more manageable. That is a useful distinction, and it keeps my expectations realistic.
I would skip it if the appeal is mainly being able to buy something I cannot otherwise afford. I would also skip it when a normal debit payment is easy, when I already have too many active schedules, or when the checkout terms are unclear. In those situations, the extra flexibility is more likely to become friction than help.
My final view is cautiously positive. The free app, broad intended Visa acceptance, and separate payment management give Zip a practical place in the shopping category. Its best use is controlled and intentional: choose the item first, inspect the complete schedule, keep future payments in the budget, and use the service only when the arrangement genuinely improves cash-flow timing. Zip is useful as a budgeting choice, not as permission to spend beyond a budget.
If that approach sounds natural to you, Zip is worth considering. If you want the simplest possible payment routine, a standard card or direct bank payment will usually be easier. The right choice depends less on the app’s download price than on whether you can comfortably manage every payment after the purchase is complete.
Pros
- Fast and efficient file compression.
- Supports a wide range of file formats.
- User-friendly interface.
- Secure encryption options.
- Seamless cloud integration.
Cons
- Limited free version features.
- Occasional ads in free version.
- Requires in-app purchases for advanced features.
- Some file formats may need external apps.
- Lacks real-time collaboration features.
FAQs for Zip
What is Zip and how does it work?
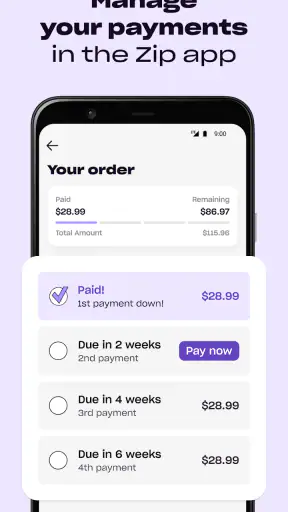
Zip is a digital payment app that allows users to make purchases and pay for them later in four installments. Users can shop at a variety of partnered retailers, both online and in-store, by linking their credit or debit card to the app. After making a purchase, payments are automatically deducted every two weeks.
Is Zip safe to use for online transactions?
Yes, Zip is designed with robust security measures to protect user information. It uses encryption to keep data secure and doesn’t store your full card details. Additionally, Zip monitors transactions for any suspicious activity to ensure a safe shopping experience. However, users should always ensure their personal devices are secure.
Are there any fees associated with using Zip?
While Zip is free to use, there are fees for late payments. If a scheduled payment fails, you may incur a late fee. It’s important to ensure adequate funds are available in your linked account. Zip may also charge a small convenience fee for each transaction, depending on your location or retailer.
Where can I use the Zip app?
Zip can be used at thousands of retailers worldwide, both online and in physical stores. The app provides a list of partner merchants within the app itself. Whether shopping for fashion, electronics, or everyday essentials, users will find a wide range of options to choose from.
What should I do if I encounter issues with my Zip account?
If you experience any problems with your Zip account, you can contact their customer support through the app or website. Zip offers a comprehensive help center with FAQs and troubleshooting guides. For urgent matters, users can reach out via email or live chat for prompt assistance.

Zip
This site provides independent information about third-party apps and is not affiliated with, or the owner, developer, or distributor of, any app featured here. App names, logos, and trademarks belong to their respective owners. Developer details are provided for reference; please contact the developer directly via us-support@care.zip.co, visit https://zip.co/us, or review their https://zip.co/us/privacy-policy.










